
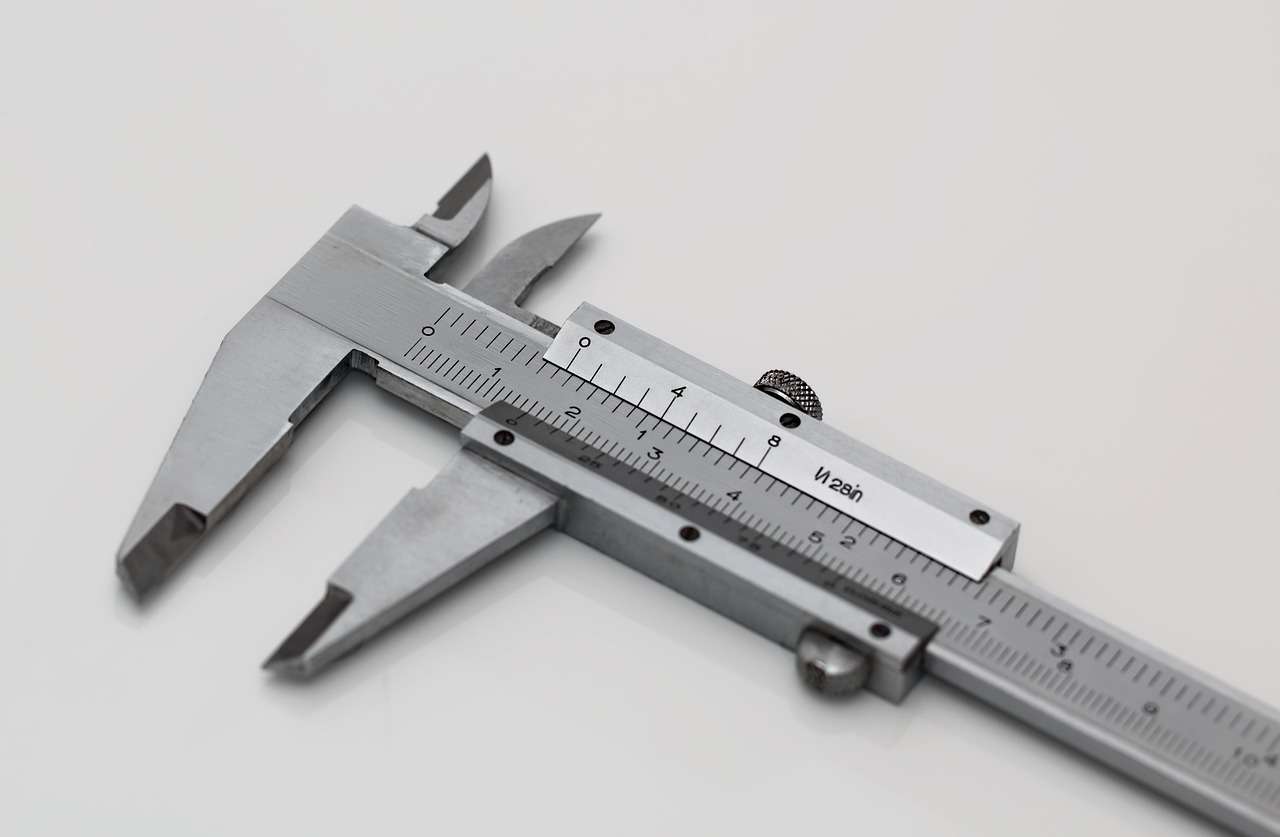
Finance Assets arranges hire purchase and leasing for UK manufacturers, test houses and inspection companies buying CMMs, industrial X-ray and CT systems, NDT equipment, vision measuring machines and materials testing equipment.
Inspection and metrology equipment finance spreads the cost over 2 to 5 years, so a business can bring inspection in-house, meet a customer’s quality requirements or take on accredited testing work without a large cash outlay. We are a broker, not a lender, so we compare quotes from our lender panel rather than offering one bank’s product.
Written by Marcus Wright, founder of Bolton Business Finance Ltd, in financial services since 2008 and a commercial finance broker since 2019. Last reviewed October 2026.
On this page
The short version
- Inspection and metrology equipment finance spreads the cost over 2 to 5 years.
- With hire purchase, the business owns the equipment after the final payment.
- CMMs from major makers have a steady used market, so they are widely funded new and used.
- Specialist X-ray, CT and NDT systems have a narrower resale market, so lenders look more closely at your business and the contracts behind the purchase.
- Finance Assets arranges this finance for limited companies and LLPs, and for sole traders and partnerships on agreements over £25,000.
| Item | Detail |
|---|---|
| Equipment covered | CMMs and portable arms, industrial X-ray and CT, ultrasonic and other NDT equipment, vision measuring machines, 3D scanners and materials testing machines |
| Terms | Usually 2 to 5 years |
| Paid upfront | Hire purchase: often a 10% deposit plus VAT. Leases: usually 1 to 3 rentals in advance |
| New or used | Both. Used CMMs and testing machines from established makers are widely funded |
| Extra costs | Probes, fixtures, software, installation, training and some room works can often be included |
| Who we help | Limited companies and LLPs, plus sole traders and partnerships on business agreements over £25,000 |
Inspection and metrology equipment we finance
Lenders will fund most inspection, measuring and testing equipment used in a business, as long as it comes from an identifiable supplier on a clear quote.
| Equipment type | Examples |
|---|---|
| Coordinate measuring machines | Bridge, gantry and horizontal arm CMMs, shop-floor CMMs, portable measuring arms and laser trackers |
| Industrial X-ray and CT | Cabinet X-ray systems, digital radiography, computed tomography (CT) for castings and additive parts, and PCB X-ray inspection |
| Non-destructive testing | Ultrasonic and phased array flaw detectors, eddy current equipment, and magnetic particle and dye penetrant inspection lines |
| Optical and vision | Vision measuring machines, optical comparators, 3D scanners, and automated optical inspection (AOI) for electronics |
| Materials testing | Tensile and universal testing machines, hardness testers, impact testers, surface roughness and form measurement |
| Environmental and product testing | Climatic and thermal shock chambers, salt spray cabinets, vibration test systems and leak testers |
We regularly see equipment from makers such as Hexagon, Zeiss, Mitutoyo, Nikon, Aberlink, Faro, Renishaw, Waygate Technologies, Instron and ZwickRoell. For X-ray and metal detection on food and packing lines, see food manufacturing equipment finance.
CMMs and metrology
Precision engineers usually buy a CMM when a customer, often in aerospace, automotive or medical work, asks for full inspection reports, or when the business is sending parts out to be measured and waiting days for results.
- Probes and software. Probe heads, styli, fixturing and measurement software can normally be funded with the machine, usually up to a set share of the total.
- Metrology rooms. Bridge CMMs often need a temperature-controlled room. Lenders will usually fund the supplier’s installation, and sometimes part of the room build, but larger building works may need to be paid separately.
- Used CMMs. CMMs from major makers can be refurbished and re-certified, so lenders fund used machines through specialist dealers, often with an upgraded controller and software.
- Customer requirements. If a customer contract or quality approval depends on the equipment, tell the lender. It shows the purchase protects existing revenue.
Industrial X-ray, CT and NDT equipment
X-ray, CT and NDT equipment is bought by foundries, fabricators, aerospace and electronics manufacturers, and by independent inspection and test houses. It is specialist equipment, which changes how lenders approach it.
- Radiation requirements. Industrial X-ray work is covered by the Ionising Radiations Regulations 2017, which means registering with or getting consent from the HSE. Self-shielded cabinet systems are the simplest to fund. Shielded rooms and bunkers are building works, so lenders may fund only part of them.
- CT systems. Industrial CT is high-value equipment with a smaller resale market. Lenders fund it, but look closely at your accounts and the work it will bring in. A larger deposit or a shorter term can help.
- Test houses. For inspection companies, the equipment is what earns the income. Lenders look at your accreditations, such as UKAS, your customer base and your record of winning repeat work.
- Portable NDT kit. Ultrasonic and eddy current units are lower value, so a single unit can fall below a lender’s minimum. Grouping kit for a new contract or team usually gives better terms.
Many fabricators add NDT alongside new production equipment. See welding machine finance and metal fabrication equipment finance.
What lenders look at on inspection equipment finance
- Maker and resale market. CMMs and testing machines from major makers have the widest resale market. More specialist systems lean more on the strength of your business.
- Age and certification. On used equipment, lenders look at the year built, the service history and whether it has been recalibrated by a recognised supplier.
- Soft costs. Software, training and installation are usually funded up to a set share. Annual calibration and service contracts normally sit outside the agreement.
- Your customers. Lenders look at which sectors you serve and how dependent you are on a few large customers.
Hire purchase, finance lease and operating lease compared
Hire purchase suits equipment you will keep for most of its working life. A lease suits you better if you want to spread the VAT or plan to upgrade. Our types of asset finance guide covers each option in more depth.
| Option | How it works | Best for |
|---|---|---|
| Hire purchase | You pay a deposit and fixed monthly payments, and own the equipment after the final payment and any option fee | CMMs, testing machines and NDT kit you will keep for years |
| Finance lease | You rent the equipment for most of its working life. At the end you extend at a low rent, or sell it for the lender and keep most of the proceeds | High-value X-ray and CT systems where spreading the VAT helps cash flow |
| Operating lease | You rent the equipment for part of its life, then hand it back or upgrade. Mostly available on new equipment from major makers | Vision and scanning systems you expect to replace as technology moves on |
Hire purchase for inspection equipment
Hire purchase is the usual choice. You pay a deposit, usually 10% plus the VAT, then fixed monthly payments, and ownership passes to you after the final payment and a small option-to-purchase fee. As the owner for tax purposes, the business may be able to claim capital allowances on the equipment.
Finance lease for inspection equipment
A finance lease keeps the upfront cost to a few rentals, and VAT is spread across the rentals rather than paid at the start. The lender owns the equipment throughout. At the end of the main term you can keep using it for a low secondary rent, or sell it on the lender’s behalf and receive most of the sale proceeds.
Operating lease for inspection equipment
An operating lease sets the rentals against what the equipment is expected to be worth at the end of the term, so the lender carries the resale risk. It is most often available on new CMMs, scanners and vision systems from major makers, sometimes through the maker’s own finance programme. At the end you hand the equipment back, extend the lease or upgrade.
Inspection equipment finance costs: a worked example
A £120,000 new bridge CMM, with a probe head, software and installation, costs about £2,688 a month on a 4-year hire purchase, or about £2,242 a month over 5 years.
| Item | 4 years | 5 years |
|---|---|---|
| Price (excl. VAT) | £120,000 | £120,000 |
| Deposit (10%) | £12,000 | £12,000 |
| VAT paid upfront | £24,000 | £24,000 |
| Monthly payment | £2,687.58 | £2,241.90 |
| Total interest | £21,004 | £26,514 |
The longer term lowers the monthly payment by about £446 but adds around £5,510 of interest. Many lenders will also defer the VAT for a few months.
Illustration calculated in October 2026, assuming an interest rate of 9% a year. It is not a quote. Your rate depends on your trading history, credit profile and the equipment.
VAT and tax on inspection equipment finance
| Option | VAT | Usual tax treatment |
|---|---|---|
| Hire purchase | Paid on the full price at the start, reclaimable if you are VAT registered | You may be able to claim capital allowances, such as the Annual Investment Allowance, and the interest is deductible |
| Finance lease | Added to each rental | Rentals are usually deductible |
| Operating lease | Added to each rental | Rentals are usually deductible |
Tax depends on your circumstances, so check the treatment with your accountant.
What lenders ask for
Most inspection and metrology equipment finance applications need the following.
- Your last 2 years of filed accounts, or management accounts and a forecast if you are newer
- Your last 3 to 6 months of business bank statements
- A quote from the supplier, showing the equipment, its serial number and year if used, and any software, probes, installation and room works separately
- Photo ID and address history for each director, member or partner
- Details of any existing finance agreements
Related guides
Who we can help
We arrange inspection and metrology equipment finance for UK limited companies and LLPs, and for sole traders and partnerships on agreements over £25,000 that are for business purposes. We are not authorised by the FCA, so we cannot arrange agreements of £25,000 or less for sole traders or partnerships of two or three partners, or finance for personal use.
Inspection and metrology equipment finance FAQs
Can I finance a used CMM?
Yes. Used CMMs from major makers are widely funded, especially when bought from a specialist dealer who has refurbished and re-certified the machine. Lenders cap the machine’s age at the end of the agreement, so an older CMM may get a shorter term.
How much does it cost to finance a CMM?
It depends on the machine, the term and your business. As an illustration, a £120,000 bridge CMM with a probe head, software and installation costs about £2,688 a month over 4 years on hire purchase at 9%, after a 10% deposit and the VAT paid upfront, or about £2,242 a month over 5 years.
Can I finance an industrial X-ray or CT system?
Yes. Cabinet X-ray and CT systems are funded by several lenders. Because the resale market is smaller, lenders look closely at your accounts and the work the system supports, and shielded room works may only be partly funded.
Can a test house or inspection company get equipment finance?
Yes. Lenders fund NDT and testing equipment for inspection companies. They look at your accreditations, your customer base and your record of repeat work, as the equipment is what produces your income.
Can software and calibration be included?
Software bought with the equipment, along with installation and training, can usually be included up to a set share of the total. Ongoing calibration and service contracts are normally paid separately.
Is it better to lease or buy inspection equipment?
Hire purchase usually works out better for CMMs and testing machines you will keep for many years, because you own them at the end and may be able to claim capital allowances. An operating lease can suit vision and scanning systems you expect to upgrade. Finance Assets compares both for each deal.
Get an inspection equipment finance quote
Tell us what you want to finance
Send us the equipment, the price and a few details about your business. We will come back with the options that are realistic and what they are likely to cost.
About the author
Marcus Wright is the owner and founder of Bolton Business Finance Ltd, which trades as Finance Assets. He has worked in financial services since 2008, beginning his career at Santander, and has been a commercial finance broker since March 2019.
He founded Bolton Business Finance in 2020 to give businesses access to the whole lending market rather than one bank’s own product range. The firm is a member of the National Association of Commercial Finance Brokers and works with a panel of 135+ lenders. Call 0161 546 9128.
Finance Assets is a trading name of Bolton Business Finance Ltd, an independent commercial finance brokerage, not a lender. We are not authorised by the Financial Conduct Authority and can only complete non-regulated introductions. All lending is for business purposes only. Registered address: Westgate House, 1 Westgate Avenue, Bolton, Greater Manchester, BL1 4RF. Company number 12495909.