
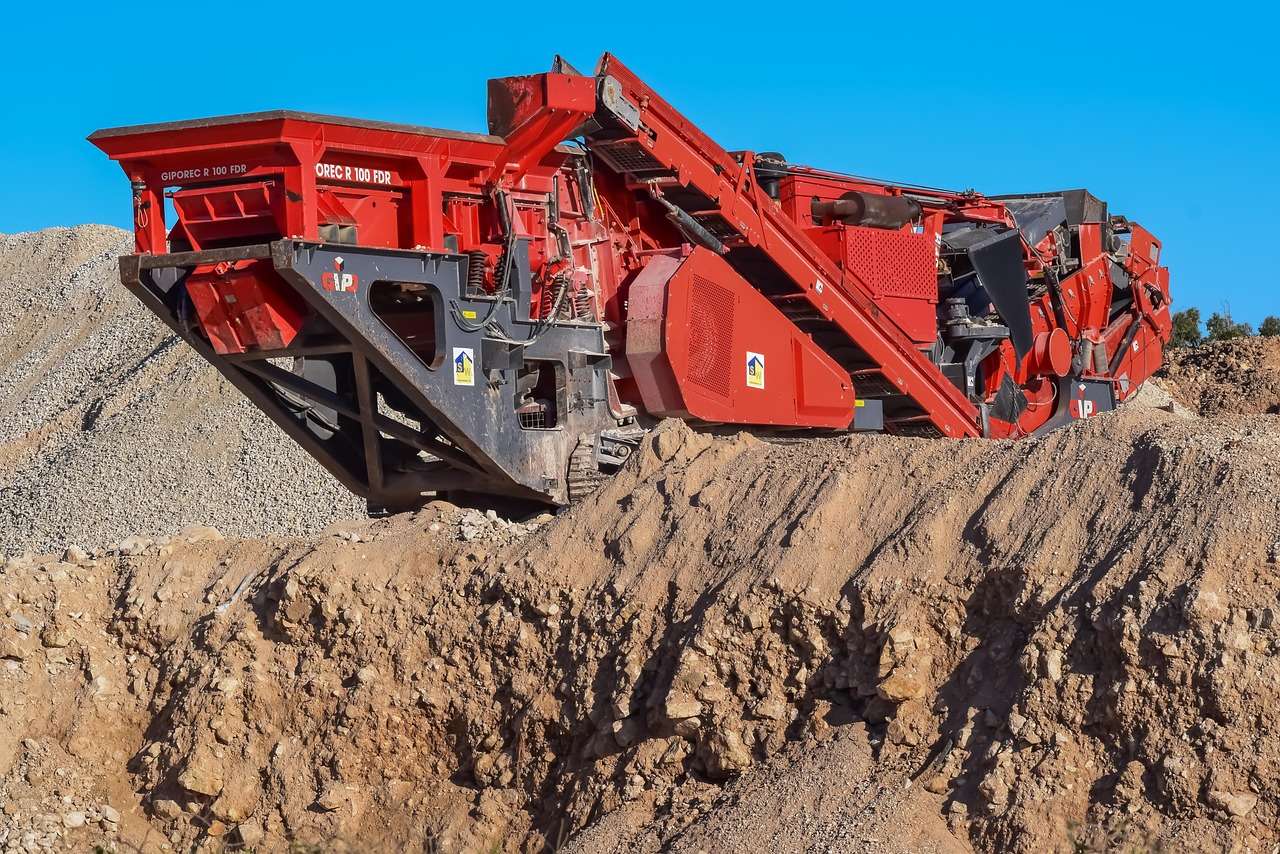
Asset finance for quarry operators spreads the cost of crushers, screens, wheel loaders, dump trucks and processing plant over 3 to 7 years, so you can add capacity without tying up working capital.
Finance Assets arranges asset finance for quarry operators, aggregates producers and contract crushing businesses, UK-wide. We compare a panel of 135+ lenders for each purchase, new or used, and lend to businesses only.
Written by Marcus Wright, founder of Bolton Business Finance Ltd, in financial services since 2008 and a commercial finance broker since 2019. Last reviewed October 2026.
On this page
The short version
- Asset finance for quarry operators covers mobile and fixed crushers, screens, washing plant, wheel loaders, excavators, dump trucks, conveyors and weighbridges.
- Used plant is widely funded, often up to around 10 years old, depending on hours and condition.
- Terms for fixed plant are usually matched to the years of permitted reserves left on the site.
- Finance Assets arranges quarry finance for limited companies and LLPs, and for sole traders and partnerships on agreements over £25,000.
| Item | Detail |
|---|---|
| Equipment covered | Crushers, screens, washing plant, wheel loaders, excavators, articulated and rigid dump trucks, conveyors, stockpilers, weighbridges and drill rigs |
| Terms | Usually 3 to 5 years for mobile plant, and up to 7 years for new fixed plant on a long-life site |
| Paid upfront | Hire purchase: often a 10% deposit plus VAT. Leases: usually 1 to 3 rentals in advance |
| Used plant | Widely funded, often up to around 10 years old at the start, depending on hours and condition |
| Not covered | Mineral rights, land, planning costs and site works, which are usually funded with a commercial loan or mortgage |
| Who we help | Limited companies and LLPs, plus sole traders and partnerships on business agreements over £25,000 |
Quarry equipment we finance
Lenders fund almost all the plant a quarry runs, from the face to the weighbridge. Mobile plant is the easiest to fund because it can be moved and resold, and fixed plant is widely funded too, usually with the supplier’s installation included.
| Equipment group | Examples |
|---|---|
| Crushing | Mobile and static jaw, cone and impact crushers |
| Screening | Mobile and static screens, scalpers and trommels |
| Washing and sand plant | Log washers, sand screws, cyclones, dewatering screens and water recycling |
| Loading | Wheel loaders and excavators. See plant hire finance for more on earthmoving machines |
| Hauling | Articulated and rigid dump trucks, tippers and HGV trailers |
| Material handling | Conveyors, stockpilers, feeders and hoppers |
| Site equipment | Weighbridges, drill rigs, dust suppression, generators and site cabins and welfare units |
| Support machines | Dozers, telehandlers and water bowsers |
Crusher and screen finance
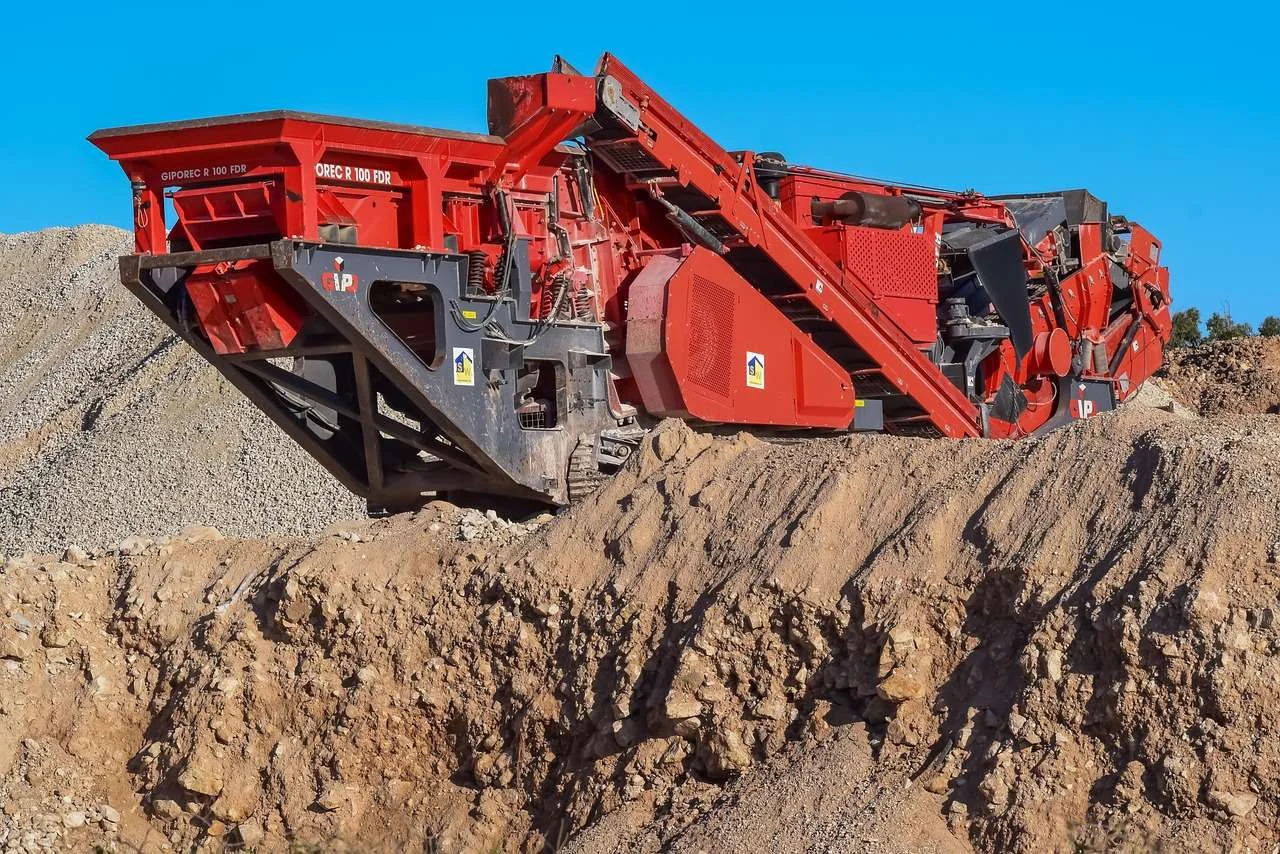
Crushers and screens are the core of most quarries and often the largest single purchase. A tracked crusher or screen that moves with the face cuts haulage on site and can be resold if plans change, which lenders like.
- New and used are both fundable. Many lenders fund used mobile crushers and screens up to around 10 years old at the start, depending on make, hours and condition.
- Trains can be funded together. A crusher, screen and conveyors bought as one train can go on one agreement, with one deposit and one payment.
- Hours matter. For used plant, lenders look at the hour meter, service history and wear parts, and may ask for an engineer’s report on high-value machines.
- Contract crushing businesses. Operators who crush on other people’s sites can fund mobile plant in the same way, with customer contracts supporting the application.
Wheel loader and dump truck finance
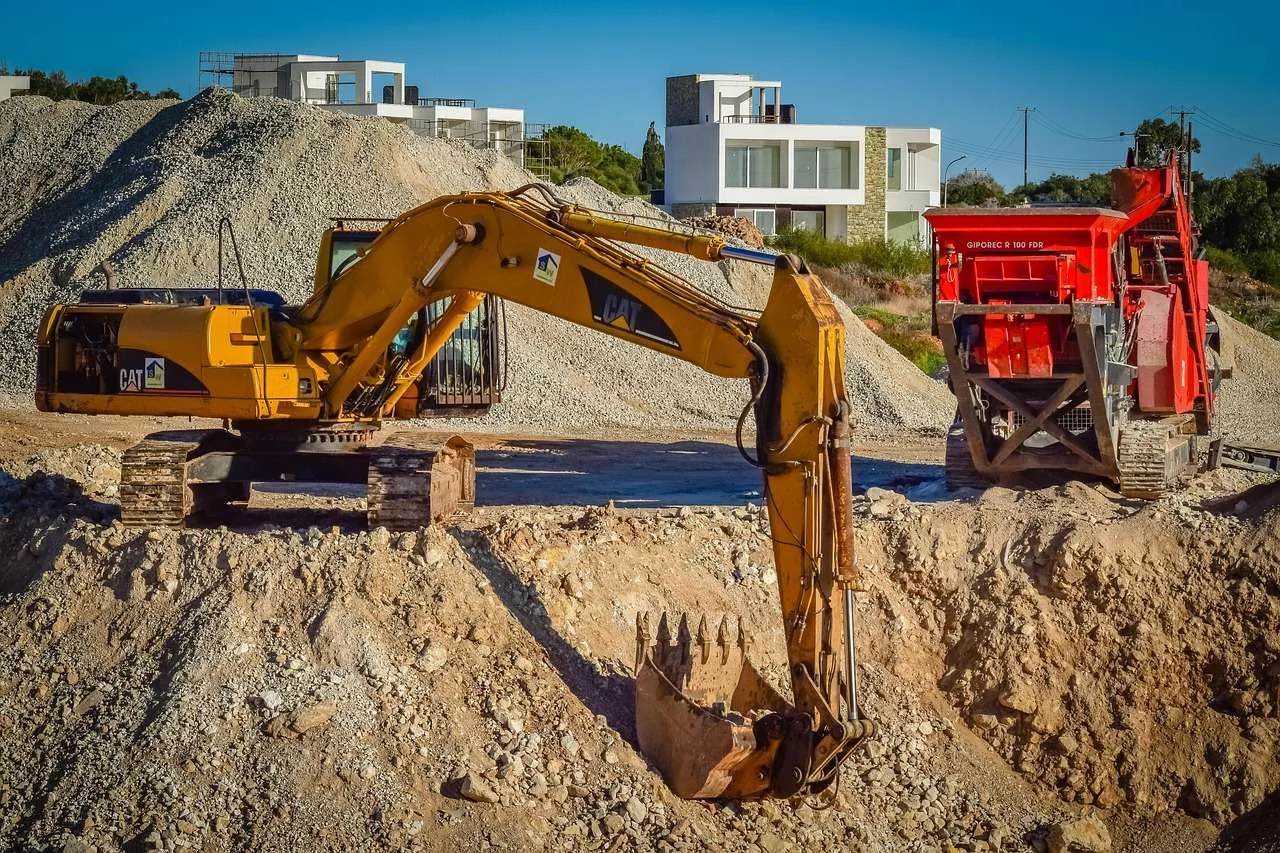
Loading shovels, excavators and dump trucks move stone from the face to the plant and from the stockpile to the customer’s lorry. They hold their value well, so they are among the easiest quarry assets to fund, new or used.
Machines you replace on a set cycle, such as wheel loaders, can suit an operating lease with an annual hours limit. Lower rentals reflect the value the machine keeps, and you hand it back at the end.
Fixed processing plant finance
Static crushing, screening and washing plant can be funded with the supplier’s installation included. Because fixed plant is harder to remove and resell, lenders look closely at how long the site has to run and usually set the term inside the remaining life of the permitted reserves.
Concrete batching plant and block making equipment are covered in our guide to asset finance for concrete and aggregates suppliers.
Finance options for quarry operators
Most quarries buy plant on hire purchase. Our types of asset finance guide covers each option in more depth.
| Type | How it works | Suits |
|---|---|---|
| Hire purchase | A deposit, then fixed payments. You own the plant after the last one | Crushers, screens and fixed plant you will keep for many years |
| Finance lease | Rentals with VAT added to each one. The lender owns the plant | Keeping the VAT outlay down on a large crushing train |
| Operating lease | Lower rentals set around the expected resale value, with an hours limit. You hand the machine back | Wheel loaders and dump trucks you replace on a set cycle |
| Refinance | A lender buys plant you own and sells it back to you over a fixed term | Raising cash for new plant or a site extension |
Hire purchase for quarry plant
Hire purchase is the usual route for quarry plant. You pay a deposit, often around 10% plus the VAT, then fixed payments, and the plant becomes yours after the final payment and a small option fee. As the owner for tax, the business may be able to claim capital allowances against the cost. A balloon payment at the end can lower the monthly cost if you expect the machine to hold its value.
Finance lease for quarry equipment
A finance lease adds VAT to each rental instead of charging it on the full price at the start, which helps with a large crusher and screen train. The lender owns the plant. At the end of the main term you can usually keep it on a small secondary rental, or sell it as the lender’s agent and keep most of the proceeds.
Operating lease for loaders and dump trucks
An operating lease suits machines you replace every 3 to 5 years. The rentals are set around the value the machine should keep, with an annual hours limit and a return condition. Going over the hours usually means an excess charge, so set the limit honestly from your current machines.
Refinancing plant you own
If the business owns crushers, loaders or dump trucks outright, a sale and hire purchase back lets a lender buy them and sell them back to you over a fixed term, so they stay on site. It can fund new plant, a site extension or working capital.
VAT and tax on quarry plant finance
Hire purchase means paying the VAT up front and may bring capital allowances, while leasing spreads the VAT across the rentals.
| Type | VAT | Tax treatment |
|---|---|---|
| Hire purchase | VAT on the full price is payable at the start, and a VAT-registered business normally recovers it on its next return | The business counts as the owner for tax, so it may be able to claim capital allowances, such as the annual investment allowance, or full expensing for companies on new plant |
| Finance lease | VAT is charged on each rental and recovered through normal returns | Rentals are usually deductible from profits |
| Operating lease | VAT is charged on each rental | Rentals are usually deductible, and the lender takes the capital allowances |
Check with your accountant how each option fits the business’s tax position before you commit.
Mobile crusher finance costs: a worked example
A new tracked jaw crusher at £400,000 costs about £8,959 a month over 4 years on hire purchase, or about £7,473 a month over 5 years.
| Item | 4 years | 5 years |
|---|---|---|
| Price (excl. VAT) | £400,000 | £400,000 |
| Deposit (10%) | £40,000 | £40,000 |
| VAT paid upfront | £80,000 | £80,000 |
| Amount financed | £360,000 | £360,000 |
| Monthly payment | £8,958.62 | £7,473.01 |
| Total interest | £70,014 | £88,380 |
The 5-year term lowers the monthly payment by about £1,486 but adds around £18,366 of interest. A well-maintained crusher keeps a strong resale value, so a balloon payment at the end is another way to bring the monthly cost down.
Illustration calculated in October 2026, assuming an interest rate of 9% a year. It is not a quote. Your rate depends on the business’s trading history, credit profile and the plant.
What lenders look for in quarry operators
Lenders look at the usual financial documents, plus the site, its reserves and how the business sells its stone.
- Accounts and bank statements. The last two or three years of accounts and recent business bank statements. Lenders expect output to follow construction demand and look at the trend rather than one year.
- Reserves and planning. How many years of permitted reserves remain, when the planning permission ends, and whether you own or lease the mineral rights. This matters most for fixed plant.
- Customers and contracts. Who buys your aggregate, including any supply contracts with contractors, merchants or ready-mix producers.
- Plant condition. For used machines, the hours, service history and an engineer’s report on high-value plant.
- Documents. Supplier quotes, plus photo ID and address history for each director, member or partner.
- Existing finance. A list of plant already on finance and what is left to pay.
Related guides
Who we can help
We arrange asset finance for quarry operators that trade as UK limited companies and LLPs, and for sole traders and partnerships on agreements over £25,000 that are for business purposes. We are not authorised by the FCA, so we cannot arrange agreements of £25,000 or less for sole traders or partnerships of two or three partners, or finance for personal use.
Asset finance for quarry operators FAQs
What can quarry operators finance?
Most plant and equipment can be financed, including mobile and fixed crushers, screens, washing plant, wheel loaders, excavators, articulated and rigid dump trucks, conveyors, stockpilers, weighbridges and drilling rigs. Mineral rights, land and site works are usually funded separately with a commercial loan or mortgage.
Can I finance a used crusher or screen?
Yes. Many lenders fund used mobile crushers and screens, often up to around 10 years old at the start of the agreement, depending on the make, hours and condition. An engineer’s report or service history helps, and the term is usually set so the machine is not too old by the end.
Can fixed processing plant be financed?
Yes. Fixed crushing, screening and washing plant can be funded with the supplier’s installation included. Lenders look at how long the site has to run, because fixed plant is harder to move and resell than a mobile machine, so terms are often matched to the remaining permitted reserves.
How long can quarry plant finance run?
Usually 3 to 5 years for mobile plant and loading equipment, and up to 7 years for new fixed processing plant on a site with long permitted reserves. The term rarely runs past the expected working life of the machine or the life of the planning permission.
Do lenders look at mineral reserves and planning permission?
For larger or fixed plant, yes. Lenders may ask how many years of permitted reserves remain, when the planning permission ends and whether the operator owns or leases the mineral rights. Mobile plant that could move to another site is less affected.
Can a quarry refinance plant it already owns?
Yes. A sale and hire purchase back lets a lender buy crushers, loaders or dump trucks you own and sell them back over a fixed term, so they stay on site. It can raise cash for new plant, a site extension or working capital.
Can a partnership or sole trader running a quarry get asset finance?
Yes, on business agreements over £25,000. Agreements of £25,000 or less for sole traders and partnerships of two or three partners are regulated, and we are not authorised by the FCA to arrange them.
Get a quarry plant finance quote
Tell us what you want to finance
Send us the plant, the price, whether it is new or used, and the hours on any used machine. We will come back with the options that are realistic and what they are likely to cost.
About the author
Marcus Wright is the owner and founder of Bolton Business Finance Ltd, which trades as Finance Assets. He has worked in financial services since 2008, beginning his career at Santander, and has been a commercial finance broker since March 2019.
He founded Bolton Business Finance in 2020 to give businesses access to the whole lending market rather than one bank’s own product range. The firm is a member of the National Association of Commercial Finance Brokers and works with a panel of 135+ lenders. Call 0161 546 9128.
Finance Assets is a trading name of Bolton Business Finance Ltd, an independent commercial finance brokerage, not a lender. We are not authorised by the Financial Conduct Authority and can only complete non-regulated introductions. All lending is for business purposes only. Registered address: Westgate House, 1 Westgate Avenue, Bolton, Greater Manchester, BL1 4RF. Company number 12495909.