
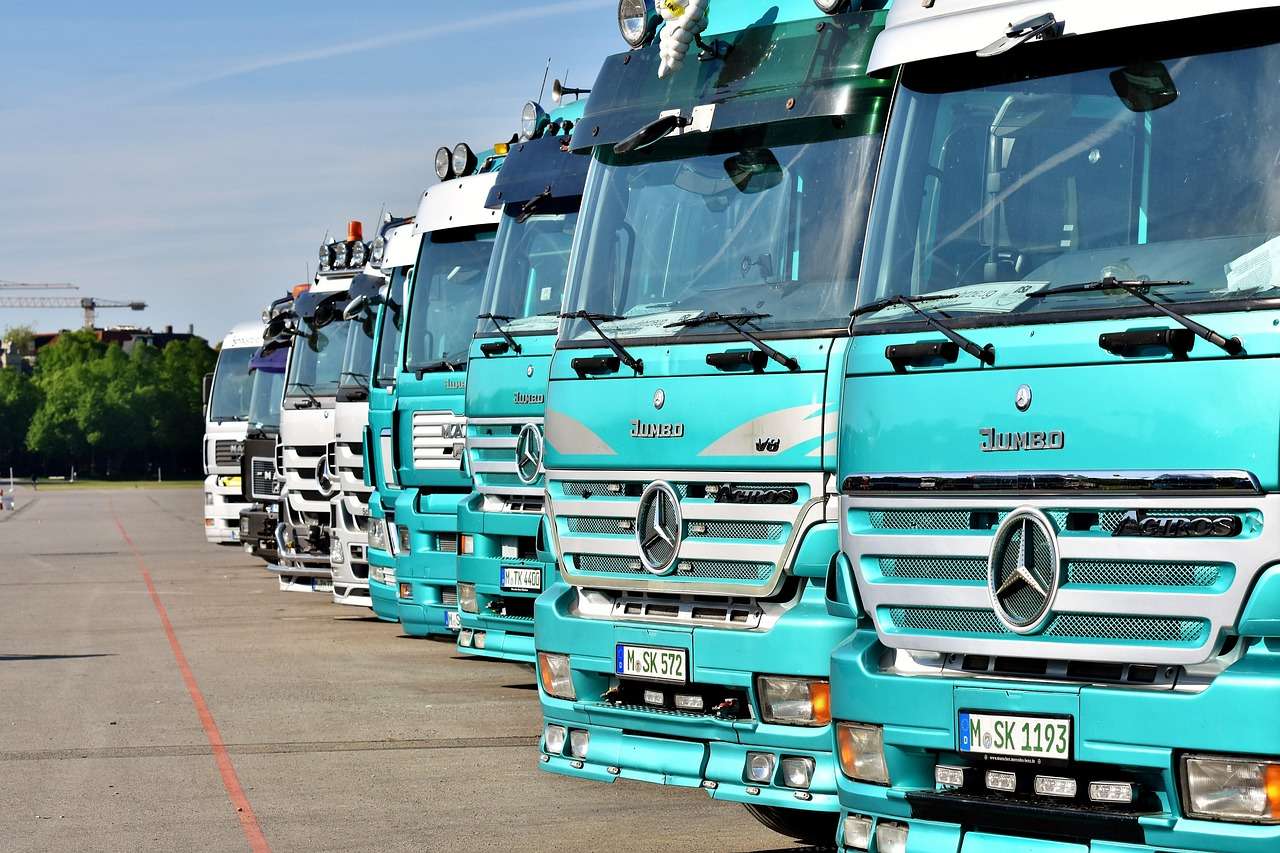
Finance Assets arranges hire purchase, leasing and contract hire for UK businesses buying new or used HGVs, tractor units and rigid trucks.
HGV finance spreads the cost of a truck over 2 to 6 years, so the cash an operator would tie up in the purchase stays available for fuel, wages and new contracts. We fund everything from a single 7.5 tonne rigid to a fleet of 44 tonne tractor units, and can put the trailers on the same agreement.
Written by Marcus Wright, founder of Bolton Business Finance Ltd, in financial services since 2008 and a commercial finance broker since 2019. Last reviewed October 2026.
On this page
The short version
- HGV finance lets an operator spread the cost of a new or used truck over 2 to 6 years.
- Hire purchase leads to ownership, usually after a deposit of around 10% plus VAT.
- Finance leases, operating leases and contract hire keep the truck with the lender and add VAT to each rental instead.
- HGVs are commercial vehicles, so VAT-registered operators can usually reclaim the VAT in full.
- Finance Assets arranges HGV finance for limited companies and LLPs, and for sole traders and partnerships on agreements over £25,000.
| Item | Detail |
|---|---|
| Vehicles covered | Tractor units, rigid HGVs from 7.5 to 32 tonnes, tippers, specialist bodies and electric trucks |
| Deal size | From a single truck to a whole fleet, with or without trailers |
| Terms | Usually 3 to 5 years, and up to 6 years on some new trucks |
| Paid upfront | Hire purchase: often a 10% deposit plus VAT. Leases and contract hire: usually 1 to 3 rentals in advance |
| New or used | Both, including ex-fleet units and many auction purchases |
| Who we help | Limited companies and LLPs, plus sole traders and partnerships on business agreements over £25,000 |
HGVs and trucks we finance
Lenders will fund almost any goods vehicle over 3.5 tonnes that is used in the business. HGV (heavy goods vehicle) is the everyday name and LGV (large goods vehicle) the legal one, and truck finance, lorry finance and HGV finance all describe the same thing.
- Tractor units, 4×2 and 6×2, with day or sleeper cabs
- Rigid HGVs from 7.5 to 32 tonnes with curtainside, box, dropside or fridge bodies
- Tippers, grab loaders and hook loaders
- Skip loaders and refuse collection vehicles
- Truck mixers and bulk tankers
- Car transporters, recovery trucks and beavertails
- Battery electric and other low emission trucks
- Bodywork, tail lifts, fridge units, cranes and telematics fitted to the chassis
For the trailers themselves, including artic contract hire on curtainsiders and fridge trailers, see HGV and artic trailer finance. For vans, buses and depot equipment, see transport and haulage finance.
HGV finance options compared
The main choice is whether you want to own the truck at the end. Hire purchase leads to ownership, while leases and contract hire keep the truck with the lender in return for lower upfront costs. Our types of asset finance guide covers each option in more depth.
| Type | How it works | At the end |
|---|---|---|
| Hire purchase | A deposit, then fixed monthly payments. You are treated as the owner for tax from the start | You own the truck after the final payment and a small option fee |
| Finance lease | Rentals over most of the truck’s working life, usually with 1 to 3 in advance | Keep it on a small secondary rental, or sell it and receive most of the proceeds |
| Operating lease | Lower rentals, priced around the truck’s expected resale value | Hand it back, extend, or move to a newer unit |
| Contract hire | A fixed rental for an agreed term and mileage, often including maintenance and tyres | Hand it back. Excess mileage and damage beyond fair wear and tear are charged |
| Type | VAT | Tax treatment, usually |
|---|---|---|
| Hire purchase | VAT on the full price is usually paid upfront, then reclaimed on your VAT return | You may be able to claim capital allowances, and the interest is usually deductible |
| Finance lease | Added to each rental | Rentals are usually an allowable business expense |
| Operating lease | Added to each rental | Rentals are usually an allowable business expense |
| Contract hire | Added to each rental, including any maintenance element | Rentals are usually an allowable business expense |
Tax depends on your circumstances, so check the treatment with your accountant before choosing.
HGV hire purchase
HGV hire purchase is the most common way operators buy trucks they will run for most of their working life. You pay a deposit, often around 10% plus the VAT, then fixed monthly payments over 3 to 5 years, and the truck is yours after the last one. A balloon payment at the end can lower the monthly cost, which is useful on tractor units that hold a strong resale value.
HGV finance lease
An HGV finance lease keeps more cash in the business, because VAT is added to each rental rather than paid on the full price at the start. The lender owns the truck, and you are responsible for running and maintaining it. At the end of the primary term you can usually keep it on a small secondary rental, or sell it to a third party and receive most of the proceeds.
HGV operating lease
An HGV operating lease prices the rentals around what the truck should be worth when it comes back, so the lender takes the resale risk and the monthly cost is lower. It suits operators who renew tractor units every 3 to 5 years to keep fuel costs down and stay within clean air zone standards. Annual mileage and condition limits are agreed at the start.
HGV and artic contract hire
HGV contract hire puts the truck and, if you choose, its servicing, repairs, tyres and annual test preparation into one fixed monthly rental. It gives the most predictable costs of any option and is widely used for artic tractor units on distribution contracts with a fixed end date. The truck goes back at the end, so check the return conditions and mileage allowance before you sign. Trailers can be put on contract hire too, as our trailer contract hire section explains.
New, used and electric trucks
New and used HGVs are both widely funded. The age of a used truck mainly affects how long a lender will lend over and how much deposit it wants.
- New truck finance on units from the major manufacturers, including build slots where the dealer takes a deposit before the chassis is built and bodied.
- Used HGVs from dealers, other operators and auctions. Lenders usually want the registration, mileage, service history and a proper invoice.
- Ex-fleet and ex-lease units, which often come with full service records that lenders like to see.
- Electric and low emission trucks, with a growing number of lenders, often alongside depot charging equipment.
- Trucks you already own can be refinanced to release cash, usually through a sale and hire purchase back.
- Replacing a truck with finance still owing, where the new lender settles the old agreement as part of the deal.
HGV finance costs: a worked example
A new £115,000 tractor unit on a 5-year hire purchase costs about £2,148 a month, or about £1,767 a month with a 25% balloon.
| Item | Standard | With 25% balloon |
|---|---|---|
| Truck price (excl. VAT) | £115,000 | £115,000 |
| Deposit (10%) | £11,500 | £11,500 |
| VAT paid upfront | £23,000 | £23,000 |
| Monthly payment (60 months) | £2,148.49 | £1,767.31 |
| Final balloon payment | None | £28,750 |
| Total interest | £25,409 | £31,289 |
The balloon saves about £381 a month, at a cost of roughly £5,880 in extra interest, because a larger balance is outstanding throughout the term. Many operators plan to settle the balloon from the sale of the unit when they replace it. Lenders can often defer the VAT for a few months as well, which helps cash flow on a fleet order.
Illustration calculated in October 2026, assuming an interest rate of 9% a year. It is not a quote. Your rate depends on your trading history, credit profile and the truck.
How HGV finance works
Most HGV finance deals follow the same five steps, whether you are adding one rigid or ten tractor units.
- Tell us about the truck: its make, model, age, mileage, price and supplier, and whether trailers are part of the deal
- We match the lenders on our panel that fund that type and age of vehicle
- We come back with the options that are realistic and what they are likely to cost
- The lender reviews your accounts, bank statements and operator’s licence and makes a credit decision
- You sign the agreement, the lender pays the supplier and the truck goes on the road
What lenders ask for
Lenders ask for the usual financial documents on HGV finance, plus the details that show the business can legally run the vehicle.
- Your last 2 years of filed accounts, or management accounts and a forecast for newer operators
- Your last 3 to 6 months of business bank statements
- Your operator’s licence number and the number of vehicles it authorises
- The supplier invoice or quote, showing the registration or chassis number
- A current fleet list and details of any existing finance agreements
- Photo ID and address history for each director, member or partner
Related guides
- HGV and artic trailer finance
- Asset finance for courier and delivery companies, for van fleets and 7.5 tonne rigids
- Asset finance for bus and coach operators
- Asset finance for waste management companies, for refuse vehicles and skip loaders
- Asset finance for concrete and aggregates suppliers, for truck mixers and tippers
- Vehicle wash equipment finance, for truck depot washes
- Types of asset finance
- All transport and haulage finance
Who we can help
We arrange asset finance for hauliers and operators that trade as UK limited companies and LLPs, and for sole traders and partnerships on agreements over £25,000 that are for business purposes. We are not authorised by the FCA, so we cannot arrange agreements of £25,000 or less for sole traders or partnerships of two or three partners, or finance for personal use.
HGV finance FAQs
What deposit do I need for HGV finance?
On hire purchase, lenders usually ask for around 10% of the price plus the VAT, and the VAT is reclaimed on your next return. Established operators with a strong track record can sometimes put down less, while newer operators or older trucks may need 15% to 25%. Leases and contract hire usually need 1 to 3 rentals in advance instead of a deposit.
Can I finance a used HGV or tractor unit?
Yes. Used tractor units and rigids from dealers, other operators and auctions are widely funded. Lenders look at the age, mileage and service history, and usually set a term that ends while the truck still has a sensible resale value, so an older unit is often funded over a shorter term or with a larger deposit.
Can a new haulage company get HGV finance?
Yes, although lenders look more closely at operators with little trading history. An operator’s licence, directors with transport experience, signed contracts or a realistic plan for the work all help. Hire purchase on a truck that holds its value is usually the easiest starting point, and a larger deposit or a personal guarantee may be asked for.
How long can HGV finance run for?
Most HGV finance runs over 3 to 5 years, and new trucks can sometimes be funded over up to 6 years. Lenders match the term to the truck’s age and expected working life. A longer term lowers the monthly payment but adds interest, and a balloon payment can lower it further.
Is HGV contract hire better than hire purchase?
It depends on how long you keep your trucks. Hire purchase usually works out cheaper over the life of a truck you will run for many years, and you own it at the end. Contract hire suits operators who replace units every 3 to 5 years and want maintenance in one fixed cost, because the truck goes back and the lender takes the resale risk.
Can I get finance on an electric HGV?
Yes, a growing number of lenders fund battery electric and other low emission trucks. Because their resale values are less established than diesel units, lenders may offer shorter terms or prefer hire purchase over operating leases. Charging equipment at the depot can often be funded alongside the trucks.
Get an HGV finance quote
Tell us about the truck
Send us the make, model, price and a few details about your fleet. We will come back with the options that are realistic and what they are likely to cost.
About the author
Marcus Wright is the owner and founder of Bolton Business Finance Ltd, which trades as Finance Assets. He has worked in financial services since 2008, beginning his career at Santander, and has been a commercial finance broker since March 2019.
He founded Bolton Business Finance in 2020 to give businesses access to the whole lending market rather than one bank’s own product range. The firm is a member of the National Association of Commercial Finance Brokers and works with a panel of 135+ lenders. Call 0161 546 9128.
Finance Assets is a trading name of Bolton Business Finance Ltd, an independent commercial finance brokerage, not a lender. We are not authorised by the Financial Conduct Authority and can only complete non-regulated introductions. All lending is for business purposes only. Registered address: Westgate House, 1 Westgate Avenue, Bolton, Greater Manchester, BL1 4RF. Company number 12495909.