
Finance Assets arranges asset finance for dairy farms, helping farm businesses fund robotic milking systems, parlours, tractors, feeder wagons, slurry equipment and livestock handling systems, new or used.
Asset finance for dairy farms spreads the cost of equipment over 3 to 7 years, so a farm can automate milking, grow the herd or replace a tractor without tying up the cash needed for feed, fertiliser and wages. We arrange dairy and farming equipment finance for farm companies and LLPs, and for sole traders and farming partnerships on agreements over £25,000.
Written by Marcus Wright, founder of Bolton Business Finance Ltd, in financial services since 2008 and a commercial finance broker since 2019. Last reviewed September 2026.
On this page
The short version
- Asset finance lets dairy farms spread the cost of milking, feeding, slurry and handling equipment and machinery over 3 to 7 years.
- Robotic milking systems and parlour equipment can be financed, but sheds, pits and concrete are usually funded another way.
- Lenders look at your milk contract and cost of production, not just last year’s profit.
- Some lenders offer seasonal payments for block-calving herds.
- We can help farm companies and LLPs, and sole traders and farming partnerships on agreements over £25,000.
| Item | Detail |
|---|---|
| Equipment covered | Robotic milking systems, parlours, milk tanks, feeder wagons, tractors, telehandlers, forage and slurry equipment, and livestock handling systems |
| Deal sizes | From a cattle crush to a multi-robot milking system |
| Terms | Usually 3 to 5 years on tractors and used machinery, and up to 7 years on robots and new milking equipment |
| Paid upfront | Hire purchase: often a 10% deposit plus VAT. Leases: usually 1 to 3 rentals in advance |
| New or used | Both, including used machines from dealers, farm sales and other farms |
| Who we help | Farm companies and LLPs, plus sole traders and partnerships on business agreements over £25,000 |
Dairy and farm equipment we finance
Lenders will fund most of the equipment a dairy farm uses, provided it comes from an established maker or dealer and can be removed and sold if needed.
| Area | Examples |
|---|---|
| Milking | Robotic milking systems, rotary and herringbone parlour equipment, milk meters, bulk milk tanks and plate coolers |
| Feeding | Diet feeder wagons, robotic feed pushers, automatic calf feeders and concentrate feeders |
| Tractors and handlers | Tractors, telehandlers, loading shovels and skid steers |
| Forage | Mowers, rakes, balers, bale wrappers and forage wagons |
| Slurry and muck | Slurry tankers, dribble bars and trailing shoes, separators, scrapers and mixers |
| Livestock handling and health | Cattle crushes, handling systems, footbaths, weigh platforms and activity monitoring collars |
| Vehicles | ATVs, utility vehicles, pickups and livestock trailers |
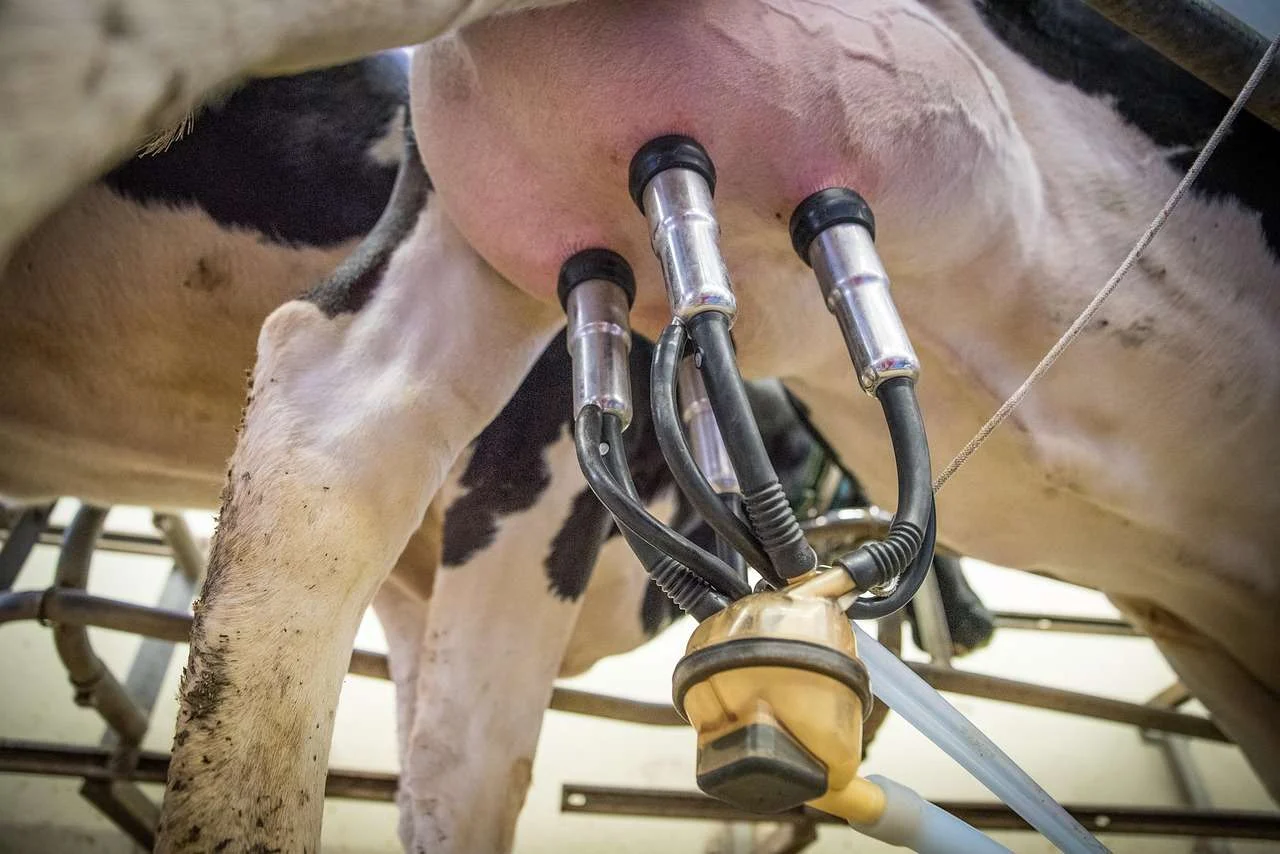
How dairy farms use asset finance
Most dairy farms use asset finance to automate milking and feeding, and to replace machinery on a regular cycle.
- Automating milking. Robots cut the labour tied to twice-daily milking, which matters on farms that struggle to recruit or keep staff.
- Growing the herd. A larger parlour, extra robots or a bigger milk tank often comes with adding cows.
- Meeting slurry rules. Rules on slurry storage and spreading push many farms towards low-emission spreading equipment and separators.
- Replacing tractors and handlers. Tractors and telehandlers work long hours, and replacing them every few years keeps repair bills and downtime down.
- Releasing cash from owned machinery. Machines you own outright can be refinanced to fund new equipment or add working capital.
Finance options for dairy farms
Most dairy farms buy equipment on hire purchase, often with a lender that specialises in agriculture. Our types of asset finance guide covers each option in more depth.
| Type | How it works | Suits |
|---|---|---|
| Hire purchase | A deposit, then fixed monthly or seasonal payments. You own the equipment after the last one | Robots, parlour equipment, tractors and machinery you will keep for years |
| Finance lease | Rentals with VAT added to each one. The lender owns the equipment | Spreading VAT on high-value equipment |
| Operating lease | Lower rentals set around the expected resale value. You hand the equipment back at the end | Tractors and handlers replaced on a regular cycle |
| Refinance | A lender buys equipment you own and sells it back to you over a fixed term | Raising cash for new equipment or working capital |
Hire purchase for farming equipment
Hire purchase for farming equipment is the most common choice on dairy farms. You pay a deposit, often around 10% plus the VAT, then fixed payments, and the equipment becomes yours after the final payment and a small option fee. Agricultural lenders often allow payments to be set monthly, quarterly or around the farm’s income.
Finance lease for farming equipment
A finance lease for farming equipment spreads the VAT across the rentals instead of paying it on the full price at the start. The lender owns the equipment. At the end of the main term you can usually keep it on a small secondary rental, or sell it for the lender and keep most of the proceeds.
Operating lease for farming equipment
An operating lease for farming equipment sets lower rentals around what the machine should be worth at the end, and you hand it back when the term finishes. It is mostly used for branded tractors and telehandlers with a strong resale market, often with an agreed limit on hours.
Hire purchase and leasing for livestock equipment
Hire purchase and finance leases for livestock equipment cover cattle crushes, handling systems, weigh platforms, calf feeders and monitoring collars. Smaller items are often grouped onto one agreement, or added to a larger deal for milking or feeding equipment. Operating leases are rare for livestock equipment, because much of it has a narrow resale market.
Robotic milking, parlours and buildings
Robotic milking systems from makers such as Lely, DeLaval and GEA are among the largest purchases a dairy farm makes, and each unit usually handles a group of around 50 to 70 cows. Lenders will fund the robots and the equipment that comes with them, such as the milk tank, cooling, feed stations and software, often over 7 years.
Buildings are different. New sheds, cubicles, concrete and parlour pits become part of the farm, so they cannot be removed and sold, and are usually funded with an agricultural mortgage or a business loan. Parlour equipment installed in a shed can often be financed even when the building work cannot. We can arrange both parts of a project at the same time.
Milk price, seasonal payments and grants
Milk prices move with the market, so lenders look at your milk contract and cost of production rather than just last year’s profit. A contract with an established buyer, and figures showing you can keep up payments when the price dips, strengthen an application.
Most dairy farms receive a milk cheque every month, which suits monthly payments. Spring and autumn block-calving herds have more seasonal income, and some lenders offer seasonal payment profiles or payment holidays around the lowest months.
Where a grant covers part of the cost of new equipment, finance can often fund the rest, or bridge the gap until the grant is paid. Check the grant rules first, because some schemes set conditions on how the equipment is bought and owned.
VAT and tax on farm equipment finance
Hire purchase means paying the VAT up front and may bring capital allowances, while leasing spreads the VAT across the rentals.
| Type | VAT | Tax treatment |
|---|---|---|
| Hire purchase | VAT on the full price is payable at the start, and a VAT-registered farm normally recovers it on its next return | The farm counts as the owner for tax, so it may be able to claim capital allowances, such as the annual investment allowance |
| Finance lease | VAT is charged on each rental and recovered through normal returns | Rentals are usually deductible from profits |
| Operating lease | VAT is charged on each rental | Rentals are usually deductible, and the lender takes the capital allowances |
Farms using the agricultural flat rate scheme instead of registering for VAT cannot reclaim VAT on purchases, so the VAT is a real cost and a lease may suit better. Capital allowances also work differently for companies and for sole traders or partnerships. Check with your accountant how each option fits the farm’s tax position before you commit.
Robotic milking finance costs: a worked example
Two robotic milking units with installation at £280,000 cost about £5,231 a month over 5 years on hire purchase, or about £4,054 a month over 7 years.
| Item | 5 years | 7 years |
|---|---|---|
| Price including installation (excl. VAT) | £280,000 | £280,000 |
| Deposit (10%) | £28,000 | £28,000 |
| VAT paid upfront | £56,000 | £56,000 |
| Amount financed | £252,000 | £252,000 |
| Monthly payment | £5,231.11 | £4,054.45 |
| Total interest | £61,866 | £88,574 |
The 7-year term lowers the monthly payment by about £1,177 but adds around £26,707 of interest. Robots are often kept for 10 years or more, so many farms choose the longer term to keep payments closer to the labour they save. A VAT-registered farm reclaims the £56,000 VAT, but a farm on the agricultural flat rate scheme cannot.
Illustration calculated in September 2026, assuming an interest rate of 9% a year and equal monthly payments. It is not a quote. Your rate depends on the farm’s trading history, credit profile and the equipment.
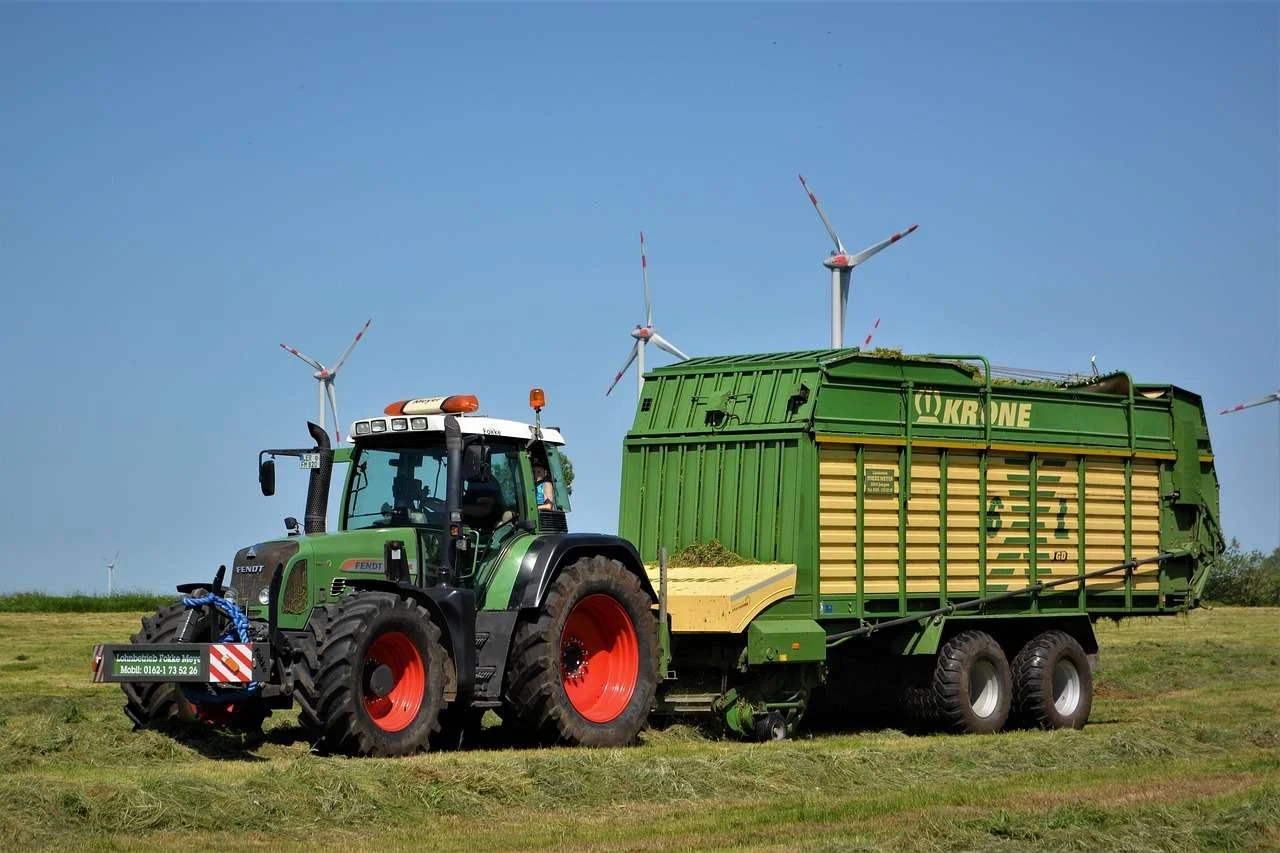
What lenders look for in dairy farms
Lenders look at the farm accounts, plus the milk contract, the herd and the land the business farms.
- Accounts and bank statements. The last two years of farm accounts, management figures if you keep them and recent bank statements.
- Milk contract. Who buys your milk, the type of contract and your current price.
- Herd and production. Herd size, yield and your cost of production per litre.
- Land and tenure. Whether the land is owned or tenanted and, for tenants, how long the tenancy runs compared with the finance term.
- Equipment details. The make, model and supplier and, for used machines, the age, hours and condition.
- Existing borrowing. Machinery already on finance, farm mortgages and overdrafts.
Related guides
Who we can help
We arrange asset finance for dairy and livestock farms that trade as limited companies and LLPs, and for sole traders and farming partnerships on agreements over £25,000 that are for business purposes. We are not authorised by the FCA, so we cannot arrange agreements of £25,000 or less for sole traders or partnerships of two or three partners, or finance for personal use.
Dairy farm finance FAQs
Can a farming partnership or sole trader get finance through you?
Yes, on agreements over £25,000 for business purposes. The lender will ask you to sign a declaration that the finance is wholly or mainly for the farm business, which takes the agreement outside consumer credit regulation. We are not authorised by the FCA, so we cannot arrange agreements of £25,000 or less for sole traders or partnerships of two or three partners. Farm companies and LLPs can be helped at any amount.
Can robotic milking systems be financed?
Yes. Robots, milk tanks, cooling and feed stations are funded regularly, often over 7 years because they have a long working life. Lenders look at the milk contract, herd size and the labour the robots will save. Building work to house them is usually funded separately with a business loan or agricultural mortgage.
Why do some farm machinery deals advertise 0% finance?
A manufacturer or dealer pays the interest to help sell the machine. These deals are genuine, but they often come with a shorter term, a larger deposit or less room to negotiate on price. It is worth comparing the cash price you could agree against the 0% deal and a standard finance quote.
Can I get seasonal payments or a payment holiday?
Often, yes. Lenders that specialise in agriculture can set payments monthly, quarterly or around the farm’s income, and some offer payment holidays in the lowest months for block-calving herds. The total you repay is usually similar, but the timing follows your cash more closely.
Can I finance livestock or farm buildings?
Asset finance is secured on equipment, so it is not usually used for cattle or buildings. A small number of specialist lenders fund livestock purchases, such as buying in heifers. Sheds, cubicles and concrete are usually funded with an agricultural mortgage or a business loan, and we can look at those alongside the equipment.
Can I raise cash against farm machinery I already own?
Yes. Through a sale and hire purchase back, a lender buys machinery you own outright and sells it back to you over a fixed term, so it stays on the farm. Branded tractors, telehandlers and feeder wagons tend to raise the most. Farms use it to fund new equipment or add working capital.
Get a dairy farm finance quote
Tell us about the equipment
Send us the equipment, the prices and whether it is new or used, plus a few details about the herd and your milk contract. We will come back with the options that are realistic and what they are likely to cost.
About the author
Marcus Wright is the owner and founder of Bolton Business Finance Ltd, which trades as Finance Assets. He has worked in financial services since 2008, beginning his career at Santander, and has been a commercial finance broker since March 2019.
He founded Bolton Business Finance in 2020 to give businesses access to the whole lending market rather than one bank’s own product range. The firm is a member of the National Association of Commercial Finance Brokers and works with a panel of 135+ lenders. Call 0161 546 9128.
Finance Assets is a trading name of Bolton Business Finance Ltd, an independent commercial finance brokerage, not a lender. We are not authorised by the Financial Conduct Authority and can only complete non-regulated introductions. All lending is for business purposes only. Registered address: Westgate House, 1 Westgate Avenue, Bolton, Greater Manchester, BL1 4RF. Company number 12495909.