
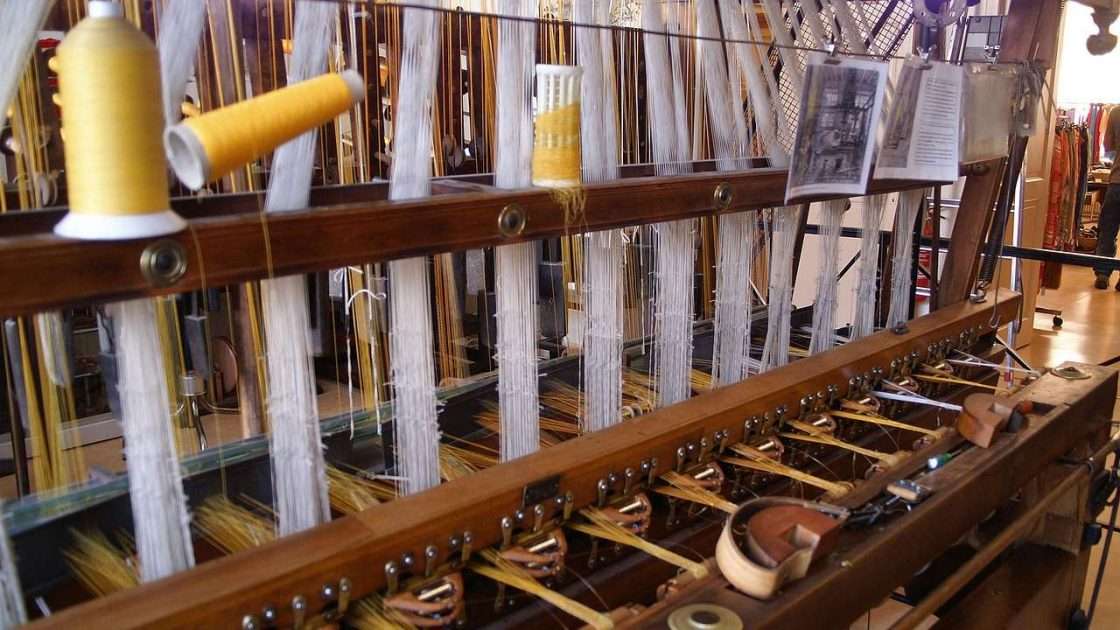
Finance Assets arranges asset finance for textile manufacturers, helping UK limited companies fund knitting machines, looms, dyeing and finishing equipment, digital textile printers and cutting rooms, new or used.
Asset finance for textile manufacturers spreads the cost of production machinery over 3 to 7 years, so a mill, knitter or dyehouse can modernise or take on a larger order without tying up the cash that pays for yarn, dyes and wages. We arrange textile machinery finance, including dyeing machine finance, for spinning, weaving, knitting, dyeing, finishing and making up.
Written by Marcus Wright, founder of Bolton Business Finance Ltd, in financial services since 2008 and a commercial finance broker since 2019. Last reviewed September 2026.
On this page
The short version
- Asset finance lets textile manufacturers spread the cost of spinning, weaving, knitting, dyeing and finishing machinery over 3 to 7 years.
- Branded knitting machines and looms keep a resale market around the world, which makes them easier to fund.
- Much textile machinery is made in Europe or Japan and bought used, and lenders will fund imported machines with the right paperwork.
- Newer dyeing machines and heat recovery cut energy, water and chemical costs, which strengthens the case for finance.
- Finance Assets arranges textile machinery finance for UK limited companies and LLPs.
| Item | Detail |
|---|---|
| Equipment covered | Spinning and yarn preparation, looms, knitting machines, nonwoven lines, dyeing machines, finishing ranges, digital textile printers, cutting and sewing equipment |
| Deal sizes | From a single sewing line to a complete dyeing and finishing range |
| Terms | Usually 3 to 5 years on used machinery, and up to 7 years on new dyeing and finishing plant |
| Paid upfront | Hire purchase: often a 10% deposit plus VAT. Leases: usually 1 to 3 rentals in advance |
| New or used | Both, including used machines from UK and European mills and dealers |
| Who we help | UK limited companies and LLPs |
Textile machinery we finance
Lenders will fund most of the machinery a textile business uses, from fibre to finished product, provided it comes from an established maker and has a second-hand market.
| Process | Examples |
|---|---|
| Spinning and yarn preparation | Carding machines, spinning frames, winding and twisting machines, warping and sizing machines |
| Weaving | Rapier, air-jet and projectile looms, Jacquard heads and weaving preparation equipment |
| Knitting | Computerised flat knitting machines, circular knitting machines, warp knitting and hosiery machines |
| Nonwovens and technical textiles | Needle punch, spunlace and thermal bonding lines, plus coating and laminating ranges |
| Dyeing | Jet and overflow dyeing machines, yarn package dyeing machines, beam dyeing machines, jiggers and colour kitchens |
| Finishing | Stenters, compactors, raising and shearing machines, dryers and fabric inspection frames |
| Printing | Digital textile printers, rotary screen printers and heat transfer presses |
| Cutting and making up | Automated cutting tables, fabric spreaders, industrial sewing lines and embroidery machines. See our embroidery machine finance guide |
How textile manufacturers use asset finance
Most textile manufacturers use asset finance to replace ageing machines and add capacity when a customer commits to more volume.
- Replacing ageing machines. Many UK mills still run machines that are decades old. Newer looms and knitting machines run faster, waste less yarn and let one operator look after more machines.
- Cutting energy and water costs. Dyeing and finishing are the most energy-hungry stages, and newer machines can bring those bills down. See dyeing machines, energy and effluent below.
- Winning shorter, faster runs. Brands buying from UK makers often want smaller batches and quicker turnaround, which suits computerised machines that change styles quickly.
- Moving into technical textiles. Nonwoven, coating and laminating lines open up medical, automotive, filtration and construction markets, where margins are often better.
- Releasing cash from owned machinery. Machines you own outright can be refinanced to fund new equipment or add working capital for yarn and stock.
Finance options for textile manufacturers
Most textile manufacturers buy machinery on hire purchase and use a finance lease where the VAT bill at the start would be large. Our types of asset finance guide covers each option in more depth.
| Type | How it works | Suits |
|---|---|---|
| Hire purchase | A deposit, then fixed monthly payments. You own the machine after the last one | Looms, knitting machines and dyeing machines you will run for many years |
| Finance lease | Rentals with VAT added to each one. The lender owns the machine | Keeping the deposit and VAT outlay down on high-value dyeing and finishing plant |
| Operating lease | Lower rentals set around the expected resale value. You hand the machine back at the end | Branded knitting machines and digital printers with a strong second-hand market |
| Refinance | A lender buys machinery you own and sells it back to you over a fixed term | Raising cash for new machines, stock or working capital |
Hire purchase for textile manufacturing machines
Hire purchase for textile manufacturing machines is the most common choice, because a well-maintained loom, knitting machine or dyeing machine can run for 15 years or more. You pay a deposit, often around 10% plus the VAT, then fixed monthly payments, and the machine becomes yours after the final payment and a small option fee. It also suits dyeing machines, which are usually bought to stay in the same dyehouse for their working life.
Finance lease for textile manufacturing machines
A finance lease for textile manufacturing machines keeps the upfront cost down, because VAT is added to each rental instead of being paid on the full price at the start. The lender owns the machine. At the end of the main term you can usually keep it on a small secondary rental, or sell it for the lender and keep most of the proceeds. It works well on finishing ranges and dyeing machines, where the VAT bill on the full price would be large.
Operating lease for textile manufacturing machines
An operating lease for textile manufacturing machines sets lower rentals around what the machine should be worth at the end, and you hand it back when the term finishes. Lenders only offer this on machines with a strong second-hand market, such as branded computerised knitting machines and digital textile printers. It is rarely available for dyeing machines or finishing ranges, which are built into the building and costly to remove.
Refinancing textile machinery you own
If you own machinery outright, a sale and hire purchase back lets a lender buy it and sell it back to you over a fixed term, so it stays on the production floor. Lenders advance more against branded knitting machines and modern looms than against older or specialist machines, which they value cautiously.
Used and imported textile machinery
Most textile machinery bought by UK manufacturers is made in Germany, Italy, Switzerland, Belgium or Japan, and much of it is bought used from mills and dealers across Europe. Lenders will fund used and imported machines, but they want more paperwork than for a new machine bought from a UK agent.
Expect to provide the supplier’s invoice, the machine’s make, model, serial number and year, and details of how it will be shipped. Where the seller wants a deposit before the machine leaves, some lenders will pay it directly and others will only pay once the machine is installed, so the timing needs agreeing at the start. Shipping, installation and commissioning can usually be included in the finance if they appear on the supplier’s invoice.
Dyeing machines, energy and effluent
Dyeing and finishing are the most energy and water hungry stages of textile making, because yarn and fabric are processed in large volumes of hot water and dried on heated ranges. Newer dyeing machines run at lower liquor ratios, meaning less water for each kilogram of fabric, which cuts the energy needed to heat it and the chemicals and effluent that go with it.
Lenders will fund the equipment that goes with this, including heat recovery systems, boilers, colour kitchens and effluent treatment plant, often on the same agreement as the dyeing machine. Showing the savings, from the supplier’s figures or your own utility bills, helps the case. A dyehouse discharging to the public sewer also needs a trade effluent consent from its water company, and lenders may ask to see it.
VAT and tax on textile machinery finance
Hire purchase means paying the VAT up front and may bring capital allowances, while leasing spreads the VAT across the rentals.
| Type | VAT | Tax treatment |
|---|---|---|
| Hire purchase | VAT on the full price is payable at the start, and a VAT-registered company normally recovers it on its next return | The company counts as the owner for tax, so it may be able to claim capital allowances, such as full expensing or the annual investment allowance on new machinery |
| Finance lease | VAT is charged on each rental and recovered through normal returns | Rentals are usually deductible from profits |
| Operating lease | VAT is charged on each rental | Rentals are usually deductible, and the lender takes the capital allowances |
Check with your accountant how each option fits your company’s tax position before you commit.
Dyeing machine finance costs: a worked example
A new jet dyeing machine with heat recovery at £225,000 costs about £5,039 a month over 4 years on hire purchase, or about £4,204 a month over 5 years.
| Item | 4 years | 5 years |
|---|---|---|
| Price including installation (excl. VAT) | £225,000 | £225,000 |
| Deposit (10%) | £22,500 | £22,500 |
| VAT paid upfront | £45,000 | £45,000 |
| Amount financed | £202,500 | £202,500 |
| Monthly payment | £5,039.22 | £4,203.57 |
| Total interest | £39,383 | £49,714 |
The 5-year term lowers the monthly payment by about £836 but adds around £10,331 of interest. A dyehouse expecting large energy and water savings may choose the shorter term, while one that wants to keep monthly costs low while new orders build may prefer 5 years.
Illustration calculated in September 2026, assuming an interest rate of 9% a year. It is not a quote. Your rate depends on your trading history, credit profile and the machinery.
What lenders look for in textile manufacturers
Lenders look at the usual financial documents, plus your customers, your premises and the machines themselves.
- Accounts and bank statements. The last two years of filed accounts, recent management accounts and three to six months of business bank statements.
- Customers and order book. Who you make for, how long you have supplied them and how much of your output goes to each. Lenders look harder where one brand or retailer takes most of it.
- Machine details. The make, model, age and supplier of each machine and, for used machines, where they are coming from.
- Premises. Your lease or ownership of the mill, and whether power, steam and drainage suit the new machine.
- Consents and permits. For dyeing and finishing, your trade effluent consent and, for larger works, an environmental permit.
- Existing finance. A list of machinery already on finance and what is left to pay.
Related guides
Who we can help
We arrange asset finance for textile manufacturers that trade as UK limited companies and LLPs. We are not authorised by the FCA, so we cannot arrange agreements of £25,000 or less for sole traders or small partnerships, or finance for personal, home or hobby use.
Textile machinery finance FAQs
What textile machinery can be financed?
Most production machinery can be financed, from carding and spinning through weaving, knitting, dyeing, finishing, printing, cutting and sewing. Support equipment such as boilers, compressors and effluent plant can be included too. Lenders prefer machines from established makers with a second-hand market, and look more cautiously at bespoke or very old machines.
Can I finance used textile machinery bought from abroad?
Yes. Used looms, knitting machines and finishing ranges from European mills and dealers are funded regularly. Lenders want the supplier’s invoice, the make, model, serial number and year of each machine, and details of shipping and installation. Older machines may be offered a shorter term so the agreement ends while the machine still has value.
Can I get finance on a dyeing machine?
Yes. Jet, overflow, package and beam dyeing machines are usually funded on hire purchase or a finance lease, often over 5 to 7 years when new. Installation, pipework and heat recovery can often go on the same agreement. Operating leases are rare for dyeing machines, because they are costly to remove from the building.
Can energy and water saving equipment be financed?
Yes. Heat recovery systems, boilers, water recycling, effluent treatment plant and efficient compressors can all be financed, either alongside new machinery or on their own. Supplier figures or utility bills showing the expected savings help the application.
Can a smaller textile business get finance?
Yes, provided it trades as a limited company or LLP. Lenders look harder at companies with less than two years of accounts, and may ask for a larger deposit, personal guarantees from the directors or evidence of orders from customers. Directors with a long record in textiles and a clean credit history make an application much easier.
Can I raise cash against textile machinery I already own?
Yes. Through a sale and hire purchase back, a lender buys machinery you own outright and sells it back to you over a fixed term, so it stays in production. Branded knitting machines and modern looms tend to raise more than older or specialist machines. Manufacturers use it to fund new equipment or add working capital for yarn and stock.
Get a textile machinery finance quote
Tell us about the machinery
Send us the machines, the prices and whether they are new or used, plus a few details about your customers and order book. We will come back with the options that are realistic and what they are likely to cost.
About the author
Marcus Wright is the owner and founder of Bolton Business Finance Ltd, which trades as Finance Assets. He has worked in financial services since 2008, beginning his career at Santander, and has been a commercial finance broker since March 2019.
He founded Bolton Business Finance in 2020 to give businesses access to the whole lending market rather than one bank’s own product range. The firm is a member of the National Association of Commercial Finance Brokers and works with a panel of 135+ lenders. Call 0161 546 9128.
Finance Assets is a trading name of Bolton Business Finance Ltd, an independent commercial finance brokerage, not a lender. We are not authorised by the Financial Conduct Authority and can only complete non-regulated introductions. All lending is for business purposes only. Registered address: Westgate House, 1 Westgate Avenue, Bolton, Greater Manchester, BL1 4RF. Company number 12495909.