
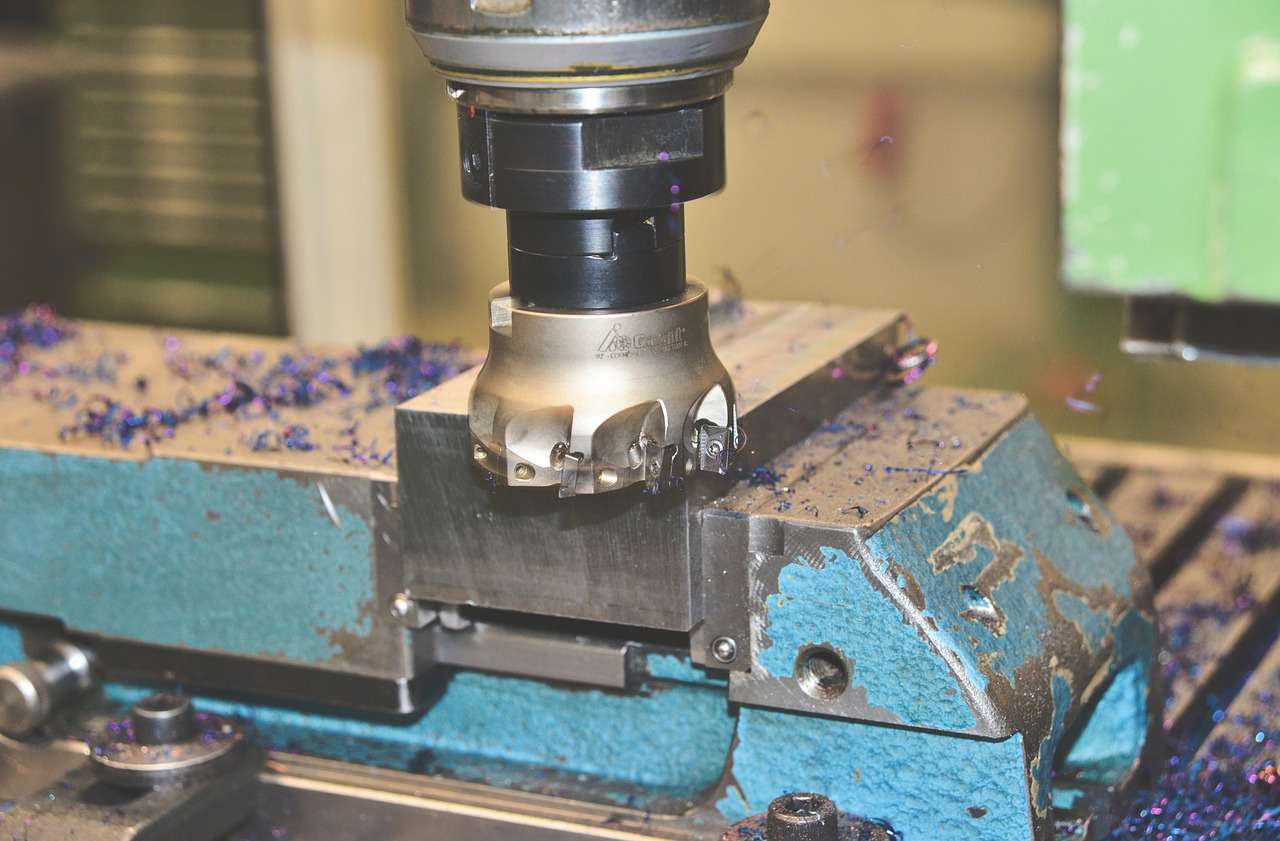
Asset finance for mechanical engineering firms spreads the cost of machine tools, fabrication and inspection equipment over 2 to 7 years, so a machine shop can add capacity without draining its working capital.
Finance Assets arranges engineering asset finance for subcontract machine shops, precision engineers, toolmakers, and maintenance and repair specialists, UK-wide including London. We compare a panel of 135+ lenders for each machine, new or used, and lend to businesses only.
Written by Marcus Wright, founder of Bolton Business Finance Ltd, in financial services since 2008 and a commercial finance broker since 2019. Last reviewed October 2026.
On this page
The short version
- Asset finance for mechanical engineering firms covers CNC machining centres, lathes, grinders, EDM machines, fabrication and inspection equipment, plus CAD/CAM software and service vans.
- Hire purchase suits core machine tools you will run for years, a finance lease spreads the VAT, and an operating lease suits equipment that dates quickly.
- Lenders look closely at your order book and customer spread, because many engineering firms rely on a few large customers.
- Finance Assets arranges engineering asset finance for limited companies and LLPs, and for sole traders and partnerships on agreements over £25,000.
| Item | Detail |
|---|---|
| Equipment covered | Machining centres, lathes, grinders, EDM, fabrication, welding, inspection and workshop equipment, CAD/CAM software and service vans |
| Terms | Usually 2 to 5 years, and up to 7 years for new, high-value machine tools |
| Paid upfront | Hire purchase: often a 10% deposit plus VAT. Leases: usually 1 to 3 rentals in advance |
| New or used | Both, including machines imported from European and Asian makers |
| Extra costs | Tooling, workholding, software, installation and training can often be included |
| Who we help | Limited companies and LLPs, plus sole traders and partnerships on business agreements over £25,000 |
Engineering equipment we finance
Lenders will fund most of the equipment a mechanical engineering firm relies on, provided it comes from an identifiable supplier and holds its resale value. Machines from established makers are the easiest to fund.
| Equipment group | Examples |
|---|---|
| Machining | 3-axis and 5-axis CNC machining centres, mill-turn centres and milling machines, plus bar feeders, pallet changers and robot loading |
| Turning | CNC lathes, sliding head lathes and manual lathes |
| Grinding and EDM | Surface, cylindrical and tool grinding machines, and wire and sinker EDM machines |
| Fabrication and welding | Press brakes, guillotines and punching machines through metal fabrication equipment finance, plus laser cutters and welding equipment |
| Inspection and metrology | CMMs, optical and vision measuring systems, and hardness and materials testing. See inspection equipment finance |
| Workshop and handling | Compressors, overhead cranes and hoists, forklift trucks and racking |
| Software and IT | CAD/CAM software, ERP systems and workstations, usually funded alongside a machine |
| Vehicles | Service vans for field and maintenance engineers |
How mechanical engineering firms use asset finance
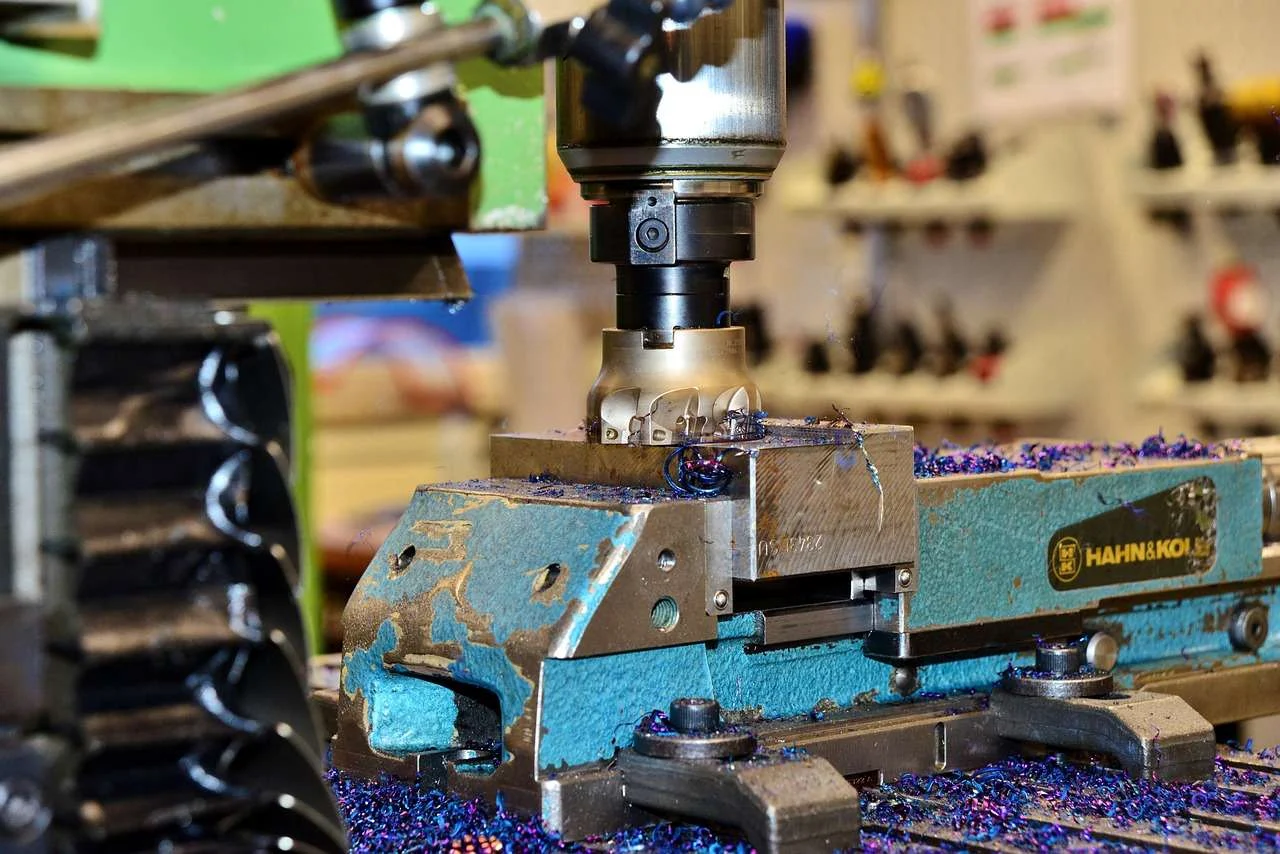
Most engineering asset finance goes on one or two core machines at a time, with tooling and software added to the same agreement.
- Bringing work in-house. A 5-axis machining centre or mill-turn centre lets a firm make parts it used to send out, and finish complex parts in fewer set-ups.
- Replacing older machines. Newer CNC machines run faster, hold tighter tolerances and need less operator time than older or manual machines.
- Running unmanned. Bar feeders, pallet changers and robot loading let machines keep cutting overnight and at weekends.
- Meeting customer requirements. Aerospace, automotive and medical customers often want inspection reports, which means a CMM and the software to go with it.
- Releasing cash from owned machines. Machines you own outright can be refinanced to fund new equipment or add working capital for materials and wages.
Finance options for mechanical engineering firms
Most engineering firms buy machine tools on hire purchase and use other options for software, vehicles and fast-changing equipment. Our types of asset finance guide covers each option in more depth.
| Type | How it works | Suits |
|---|---|---|
| Hire purchase | A deposit, then fixed monthly payments. You own the machine after the last one | Machining centres, lathes, grinders and CMMs you will run for many years |
| Finance lease | Rentals with VAT added to each one. The lender owns the machine | Keeping the deposit and VAT outlay down on a large machine order |
| Operating lease | Lower rentals set around the expected resale value. You hand the equipment back at the end | CAD/CAM workstations and test equipment that date quickly |
| Contract hire | Fixed rentals for a set term and mileage, often with maintenance included | Service vans for field engineers |
| Refinance | A lender buys machinery you own and sells it back to you over a fixed term | Raising cash for new machines or working capital |
Hire purchase for mechanical engineering firms
Hire purchase for mechanical engineering firms is the usual route for machine tools, because a well-maintained machining centre or lathe stays productive for many years. You pay a deposit, often around 10% plus the VAT, then fixed monthly payments, and the machine becomes yours after the final payment and a small option fee. As the owner for tax, you may be able to claim capital allowances against the cost.
Finance lease for mechanical engineering
A finance lease for mechanical engineering equipment adds VAT to each rental instead of charging it on the full price at the start, which helps when several machines arrive at once. The lender owns the equipment. At the end of the main term you can usually keep it on a small secondary rental, or sell it on the lender’s behalf and keep most of the proceeds.
Operating lease for mechanical engineering
An operating lease for mechanical engineering sets lower rentals around what the equipment should be worth at the end, and you hand it back when the term finishes. It suits CAD/CAM workstations, test equipment and some branded machine tools with a strong second-hand market, where you expect to upgrade within a few years.
Contract hire for mechanical engineering firms
Contract hire for mechanical engineering firms is used mainly for service vans for field and maintenance engineers. You pay a fixed monthly rental for an agreed term and mileage, maintenance can be included, and the van goes back at the end, so there is no resale value to worry about.
Refinancing engineering machinery you own
If you own machines outright, a sale and hire purchase back lets a lender buy them and sell them back to you over a fixed term, so they stay on the shop floor. Lenders advance more against modern CNC machines from established makers than against older or manual machines.
Used and imported machine tools
Used machine tools from dealers are widely funded, and some lenders also fund auction and private purchases after an inspection or valuation. Many machines are made in Germany, Switzerland, Japan or Taiwan, and lenders will fund imports, with some paying overseas suppliers directly. Older machines may be offered a shorter term, because lenders usually cap the machine’s age at the end of the agreement.
Expect to provide the supplier’s invoice, and the make, model, serial number and year of each machine. Delivery, rigging, installation and training can usually be included if they appear on the supplier’s invoice.
VAT and tax on engineering asset finance
Hire purchase means paying the VAT up front and may bring capital allowances, while leasing spreads the VAT across the rentals.
| Type | VAT | Tax treatment |
|---|---|---|
| Hire purchase | VAT on the full price is payable at the start, and a VAT-registered company normally recovers it on its next return | The company counts as the owner for tax, so it may be able to claim capital allowances, such as full expensing or the annual investment allowance on new machinery |
| Finance lease | VAT is charged on each rental and recovered through normal returns | Rentals are usually deductible from profits |
| Operating lease | VAT is charged on each rental | Rentals are usually deductible, and the lender takes the capital allowances |
Check with your accountant how each option fits your company’s tax position before you commit.
Machining centre finance costs: a worked example
A new 5-axis machining centre with tooling and installation at £150,000 costs about £3,359 a month over 4 years on hire purchase, or about £2,802 a month over 5 years.
| Item | 4 years | 5 years |
|---|---|---|
| Price including tooling and installation (excl. VAT) | £150,000 | £150,000 |
| Deposit (10%) | £15,000 | £15,000 |
| VAT paid upfront | £30,000 | £30,000 |
| Amount financed | £135,000 | £135,000 |
| Monthly payment | £3,359.48 | £2,802.38 |
| Total interest | £26,255 | £33,143 |
The 5-year term lowers the monthly payment by about £557 but adds around £6,888 of interest. A firm with the machine already booked on a long contract may choose the shorter term, while one building up new work may prefer the lower payment.
Illustration calculated in October 2026, assuming an interest rate of 9% a year. It is not a quote. Your rate depends on your trading history, credit profile and the machinery.
What lenders look for in mechanical engineering firms
Lenders look at the usual financial documents, plus your customers, your accreditations and the machines themselves.
- Accounts and bank statements. The last two years of filed accounts, recent management accounts and three to six months of business bank statements.
- Customers and order book. Who you make for and how much of your work goes to each. Lenders look harder where one or two customers take most of it, and long-term supply agreements with your largest customers help.
- Accreditations. Quality approvals such as ISO 9001, or AS9100 for aerospace work, show a lender the business is established.
- Machine details. The make, model, age and supplier of each machine and, for used machines, where they are coming from.
- Documents. Supplier quotes, plus photo ID and address history for each director, member or partner.
- Existing finance. A list of machinery already on finance and what is left to pay.
Related guides
Who we can help
We arrange asset finance for mechanical engineering firms that trade as UK limited companies and LLPs, and for sole traders and partnerships on agreements over £25,000 that are for business purposes. We are not authorised by the FCA, so we cannot arrange agreements of £25,000 or less for sole traders or partnerships of two or three partners, or finance for personal use.
Asset finance for mechanical engineering FAQs
What can mechanical engineering firms finance?
Most engineering equipment can be financed, including CNC machining centres, lathes, grinders, EDM machines, press brakes, laser cutters, welding equipment, CMMs and workshop kit such as compressors and cranes. CAD/CAM software and service vans can be funded too. Machines from established makers with a second-hand market are the easiest to fund.
Can I finance a used or imported machine tool?
Yes. Used machine tools from dealers are widely funded, and some lenders fund auction and private purchases after an inspection or valuation. Imported machines can be funded too, with some lenders paying overseas suppliers directly. Older machines may be offered a shorter term, because lenders usually cap the machine’s age at the end of the agreement.
How long can engineering asset finance run?
Most engineering asset finance runs for 2 to 5 years, and up to 7 years for new, high-value machine tools such as 5-axis machining centres. The term should match how long the machine will stay productive, so the payments finish before it needs replacing. Used machines are usually offered shorter terms.
Can tooling, software and installation be included?
Yes. Tooling, workholding, CAD/CAM software, delivery, installation and training can usually go on the same agreement as the machine, provided they appear on the supplier’s invoice. Lenders often limit these extras to a set share of the total, because they have little resale value on their own.
Does relying on a few large customers affect my application?
It can. Lenders look at how much of an engineering firm’s work goes to its largest customers, because losing one could hit cash flow. A spread of customers, long-term supply agreements or a strong order book all help. It rarely stops a deal, but it can affect the deposit or term offered.
Can a new engineering business get asset finance?
Yes, although lenders look more closely at businesses with less than two years of accounts. They may ask for a larger deposit, personal guarantees from the directors or evidence of the work the machine will be used for. Directors with a long record in engineering and a clean credit history make an application easier.
Can I raise cash against machines I already own?
Yes. Through a sale and hire purchase back, a lender buys machines you own outright and sells them back to you over a fixed term, so they stay in production. Modern CNC machines from established makers raise more than older or manual machines. Firms use it to fund new equipment or add working capital.
Get an engineering asset finance quote
Tell us about the machine
Send us the machine, the price and whether it is new or used, plus a few details about your customers and order book. We will come back with the options that are realistic and what they are likely to cost.
About the author
Marcus Wright is the owner and founder of Bolton Business Finance Ltd, which trades as Finance Assets. He has worked in financial services since 2008, beginning his career at Santander, and has been a commercial finance broker since March 2019.
He founded Bolton Business Finance in 2020 to give businesses access to the whole lending market rather than one bank’s own product range. The firm is a member of the National Association of Commercial Finance Brokers and works with a panel of 135+ lenders. Call 0161 546 9128.
Finance Assets is a trading name of Bolton Business Finance Ltd, an independent commercial finance brokerage, not a lender. We are not authorised by the Financial Conduct Authority and can only complete non-regulated introductions. All lending is for business purposes only. Registered address: Westgate House, 1 Westgate Avenue, Bolton, Greater Manchester, BL1 4RF. Company number 12495909.